Revenue shows you who buys the most. Cost to serve shows you who is worth keeping.
Some customers announce themselves the moment their names appear on a sales report. They place large orders, they account for a meaningful share of annual revenue, and their logos carry credibility that helped the company win other work. When leadership reviews the customer list, these accounts rise naturally to the top, and nobody questions why.
Then someone asks how much profit the company actually makes from them, and the room gets quieter.
Most businesses can name their largest customers without hesitating. Far fewer can calculate what it costs to serve each one. Sales reports capture what customers buy, and they rarely capture the estimating, customization, meetings, support calls, rework, expedited shipping, collections activity, inventory carrying, discounts, and senior leadership attention that the relationship consumes after the invoice goes out. That gap between what a customer pays and what a customer costs is where a great deal of profit quietly disappears.
The short answer
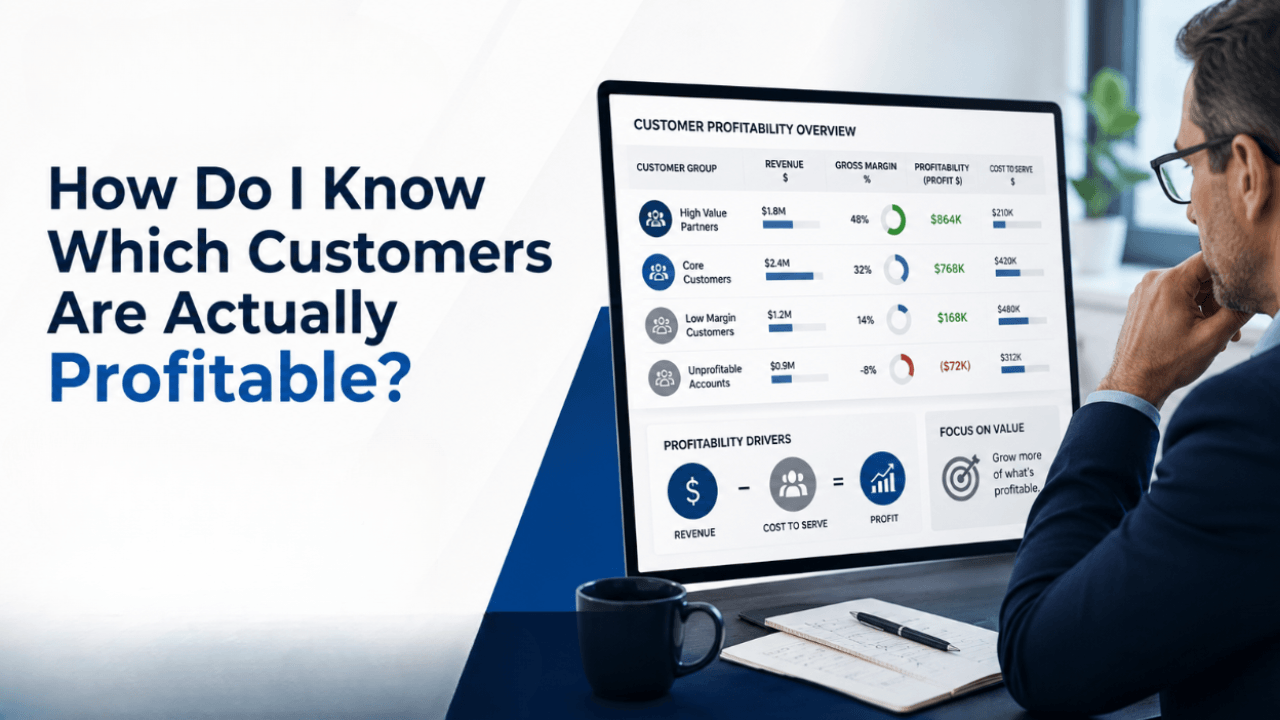
To determine which customers are actually profitable, calculate the revenue you retain from each customer and subtract every cost required to win, deliver, support, and collect on that relationship. The working formula is straightforward: customer revenue, less discounts, refunds, and credits, less the direct cost of goods or labor, less the customer’s cost to serve, equals customer profit.
The calculation does not need to be precise to be useful. It does need to go further than revenue or gross margin, because those two numbers are exactly what hide the problem. Your largest customer is not automatically your most profitable one, and your smallest is not automatically your least valuable.
The scale of the distortion is larger than most owners expect. In the research that established this field, Robert Kaplan and V.G. Narayanan found that the most profitable twenty percent of a company’s customers typically generate between 150 and 300 percent of its total profits, with the middle band roughly breaking even and the least profitable customers destroying the difference. Their earlier case study of the Swedish manufacturer Kanthal made the point concretely: forty percent of customers were profitable and produced 250 percent of total profits, while the least profitable ten percent consumed the equivalent of 120 percent of them.
Read that carefully, because it is the whole argument. A company earning a million dollars in profit may be earning two million from its good customers and giving one million back to its worst ones. Nothing on the income statement shows this.
Why revenue is such a poor proxy
Picture two customers who each generate $250,000 a year.
The first buys standardized services, plans work well in advance, communicates through a single decision maker, pays within fifteen days, and rarely changes anything after the work is scoped. The second negotiates a substantial discount, requires custom reporting, schedules frequent check-in meetings, revises requirements after production begins, pays in sixty to ninety days, and routinely escalates service issues to senior leadership.
Their revenue is identical, and their economics are not remotely comparable. The first customer produces reliable profit with minimal friction. The second may consume so much labor, working capital, and management attention that the account contributes very little, and in some cases loses money outright. This is why customer profitability analysis examines the whole relationship rather than the invoice total.
Start with the revenue you actually keep
The first step is not adding up invoices, it is calculating net customer revenue. Begin with total sales tied to the customer, then subtract contractual discounts, volume rebates, refunds, credits, returns, promotional allowances, uncollectible amounts, and any other concession specific to that account.
A customer who buys $500,000 a year and receives $50,000 in discounts and credits is not a $500,000 customer. The analysis starts at $450,000. This sounds too obvious to mention, and businesses evaluate customers on gross sales reports constantly, which never show how much revenue was conceded to win or keep the relationship in the first place.
Add the direct cost of delivering the work
Next, identify the costs traceable to what the customer actually receives. For a manufacturer this usually begins with cost of goods sold. For a professional services firm, direct labor is typically the largest line. For a distributor, freight, warehousing, and order handling can move the result substantially. Materials, production labor, subcontractors, sales commissions, packaging, delivery, project-specific software, travel, and equipment usage all belong here.
Subtracting direct costs from net revenue produces a contribution figure, which is genuinely useful and still incomplete. The costs that turn a good-looking account into a poor one almost always appear after this point.
Then measure cost to serve, which is where the answer usually lives
Cost to serve is everything required to maintain and fulfill the relationship beyond the product or service itself. These costs are easy to miss precisely because they are distributed across departments, and no single expense looks alarming on its own.
Sales and onboarding. Consider what happens before a customer becomes fully operational: proposals, contract negotiation, vendor registration, security reviews, legal review, custom onboarding, initial training, data migration, and integration work. A large contract can easily justify heavy onboarding when the relationship runs for years. The same investment looks very different when the customer leaves after seven months.
Service and support. Some customers simply need more. Support calls, account management meetings, training sessions, custom reports, site visits, rush requests, after-hours help, and executive involvement all consume capacity that never appears on the invoice. The point of tracking this is not to penalize customers for asking for help, since support is part of most strong relationships. The point is to find out whether your pricing reflects the service you are actually delivering.
Exceptions and rework. Standard processes cost less than exceptions, reliably and predictably. Custom packaging, unique billing procedures, modified production runs, frequent order changes, manual data entry, narrow delivery windows, small and frequent orders, and repeated corrections each add cost. One exception is manageable. A relationship built entirely on exceptions is difficult to scale profitably, and it tends to get harder rather than easier as the company grows.
The cost of waiting to be paid. A sale is not the same thing as collected cash, and this gap has widened recently. Intuit QuickBooks reported in July 2026 that fifty-nine percent of small businesses had invoices overdue by thirty days or more, up sharply from forty-seven percent the previous year, with affected businesses owed an average of $17,700. Nearly half of owners said standard payment processing times created critical or moderate cash flow gaps even after customers had paid, and fifty-nine percent had paid extra fees simply to access money they had already earned. Xero’s U.S. Small Business Insights data points the same direction, showing small businesses waiting an average of 28.8 days to be paid in the first quarter of 2026, with invoices arriving 9.0 days late on average.
Slow payment does not automatically make a customer unprofitable. It does mean you are financing that customer’s operations with your own working capital, and when the delay forces you to draw on a line of credit or defer an investment, the cost is real and quantifiable.
Concentration risk. Some costs never appear on an income statement at all. An account representing thirty-five percent of revenue may be highly profitable today and still expose the company to serious risk, since losing it could force layoffs, strand equipment, and disrupt cash flow all at once. Writing in Forbes, one advisor treats a single client accounting for ten to fifteen percent of gross revenue as the point where concentration becomes a genuine problem, particularly for owners who may eventually want to sell.
A worked example
Consider a business services company with a customer generating $120,000 in annual billings. The customer receives $5,000 in discounts, leaving $115,000 in net revenue.
The company then identifies $48,000 in direct employee labor and $7,000 in contractor and software costs, followed by $22,000 in cost to serve, made up of $9,000 in account management time, $6,000 in revisions and rework, $4,000 in travel and onsite meetings, and $3,000 in billing and collection activity.
Net revenue of $115,000 less $48,000 in direct labor, less $7,000 in direct project costs, less $22,000 in cost to serve, leaves $38,000 in customer profit. Measured against net revenue, that is a margin of roughly 33 percent, or about 32 percent measured against gross billings.
Now take a second customer billing the same $120,000 who requires an additional $40,000 in customization, rework, support, and senior leadership involvement. That account does not simply earn less. It loses roughly $2,000, while appearing on every sales report as the equal of the first.
The purpose of the exercise is not to produce a number you could defend to an auditor. It is to reveal differences that revenue reports conceal.
How to handle overhead without fooling yourself
This is where the analysis gets genuinely difficult. Rent, insurance, leadership salaries, information technology, accounting, and general administration support the whole organization, and assigning them to individual customers requires judgment.
Allocating overhead by revenue share is simple and tends to punish your best accounts, making large, efficient customers look expensive purely because they buy more. Allocating by activity produces a more honest picture, connecting customer service costs to support hours, warehouse costs to order volume and storage, and billing costs to invoice count and collection effort. Activity-based costing is the method the underlying research relies on, for the straightforward reason that it links costs to whatever causes them.
The tradeoff is effort. Greater precision demands better data, and for most small businesses the right starting point is a reasonable estimate built around the largest cost differences among customers rather than a full accounting model. False precision is not the goal. Better decisions are.
Four segments, and what each one needs
Once the numbers exist, customers sort into four practical groups, and the useful work is deciding what each group requires.
High profit and well matched customers produce healthy margins, fit your capabilities, pay reliably, and are efficient to serve. The question worth asking here is why these relationships work so well, because the answer usually describes your strongest target market or your real competitive advantage.
Profitable but demanding customers remain financially attractive while consuming considerable attention, customization, or capacity. Many are worth keeping. Leadership still needs to decide whether the service model survives the company doubling in size.
Low profit with room to improve is often the largest opportunity in the analysis, because the relationship already exists. Updated pricing, minimum order sizes, revised service levels, standardized processes, shorter payment terms, and better scheduling can move these accounts substantially without winning a single new customer.
Persistently unprofitable customers consume more than their revenue justifies in a way that resists easy fixing. Termination is not the automatic answer, and at some point keeping such an account does prevent the organization from serving better-fitting customers, developing its people, and investing in growth.
What to actually do with an unprofitable customer
Discovering that an account loses money does not mean the relationship should end, and moving too quickly here is expensive in its own right. Research by Frederick Reichheld of Bain & Company, widely cited in the Harvard Business Review, found that increasing customer retention rates by five percent increases profits by between twenty-five and ninety-five percent, a range that varies considerably by industry and is worth treating as a direction rather than a promise. The economics of keeping customers are strong enough that fixing an account should generally be attempted before ending it.
Raising the price is appropriate when the customer receives more value or service than the agreement reflects, and the conversation works far better when it names specifics. A vague message about rising costs persuades nobody. A specific discussion of delivery patterns, customization, revision cycles, or expanded scope usually lands, because the customer has noticed the same things you have.
Redesigning the service often achieves more than a price increase. Reducing meeting frequency, standardizing reports, capping revisions, defining support hours, consolidating orders, and automating administrative work can restore margin while making the relationship easier for both parties.
Changing the terms addresses a different problem. Deposits, retainers, shorter payment windows, minimum commitments, and rush charges align the agreement with the work being performed, and they should clarify expectations rather than ambush anyone.
Cross-selling improves total account profitability only when the additional work carries healthy margins. Adding more low-margin revenue to a low-margin account solves nothing.
Accepting lower profit deliberately is legitimate when the customer provides entry to a market, a reference that opens doors, predictable baseline volume, or learning that improves the offering. The decision should be explicit and time limited, because “strategic” tends to become the permanent explanation for an account nobody wants to confront.
Ending the relationship is sometimes the responsible choice, particularly when an account damages profitability, employee morale, service quality, or your capacity to pursue better work. Handle it with real notice and clear communication. A difficult customer does not need to become a reputation problem.
Where this analysis will mislead you
Customer profitability work has genuine limitations, and pretending otherwise produces bad decisions dressed up as rigor.
Your data is probably incomplete, since employee time, support activity, and exception costs are rarely tracked well, which means early calculations rest on estimates. A single period can mislead badly, because a customer may look unprofitable during onboarding and become excellent afterward, or look strong in a quiet year and expensive during implementation. Reviewing a meaningful stretch of time matters more than precision within any one of them.
Cost allocation cuts both ways. Loading too much general overhead onto an account makes a healthy customer look like a problem, and loading too little flatters it. Treat the output as a decision tool rather than accounting truth.
The subtler risk is cultural. Sales leaders can feel punished for bringing in demanding customers, service teams can start viewing customers as problems, and employees can begin optimizing for easy work rather than valuable work. Leadership sets that frame, and the frame is that the objective is designing better relationships, not sorting people into good and bad.
How often should you review this?
Annually is a reasonable minimum for most established businesses. Quarterly makes sense when costs are moving quickly, when the company is scaling, when labor is the dominant expense, when service requirements vary widely between customers, when capacity is constrained, or when a small number of accounts represent a large share of revenue. Leadership should also run the numbers before renewing a major contract or agreeing to a significant expansion of scope, which is the moment the information is worth the most and is least often available.
Doing this without sophisticated software
A spreadsheet is enough for a first pass. Select ten to twenty customers covering your highest revenue accounts, your fastest growing ones, the most demanding ones, several considered easy to serve, and a few smaller relationships for contrast. For each, estimate net annual revenue, direct product or labor cost, sales and onboarding time, account management and support time, rework and exception costs, delivery and logistics, billing and collection effort, and the resulting profit and margin. Note strategic value and risk alongside the number.
The results will not reconcile perfectly with your financial statements, and they will still be worth having. The first real benefit is usually not the spreadsheet. It is the conversation that happens when sales, operations, finance, and leadership compare what each of them experiences in the same customer relationship, and discover they have been describing four different companies.
When to involve an accountant, a CFO, or a business coach
An accountant or financial professional can tell you whether your underlying data is sound and whether costs are being allocated sensibly. A fractional or full-time CFO becomes valuable when the company needs forecasting, pricing analysis, and ongoing margin management rather than a one-time exercise.
A business coach replaces neither, and it is worth being clear about the difference. Financial professionals help clarify what the numbers say. Coaching helps owners decide what they are prepared to do about them, which is usually the harder problem, since the analysis tends to surface decisions about pricing, capacity, and specific long-standing relationships that leadership has been avoiding for years.
Frequently asked questions
What is customer profitability? Customer profitability is the profit a business earns from a customer relationship after subtracting the direct and indirect costs of acquiring, serving, supporting, and retaining that customer.
How do you calculate customer profitability? Start with net customer revenue after discounts, refunds, and credits. Subtract direct product or service costs, then subtract customer-specific sales, onboarding, support, logistics, administrative, financing, and exception costs.
What is cost to serve? Cost to serve is the total operational cost of fulfilling and maintaining a customer relationship beyond the basic cost of the product or service, including support, order processing, delivery, returns, customization, reporting, collections, and management time.
Can a high-revenue customer be unprofitable? Yes, and it is common. Discounts, customization, support demands, rework, slow payment, and logistics can consume the entire margin an account generates. Kaplan and Narayanan’s research found that the least profitable customers in a typical portfolio destroy a substantial share of the profits earned elsewhere.
Should I fire every unprofitable customer? No. Establish first whether the low profitability is temporary, whether the relationship carries strategic value, and whether pricing, terms, service levels, or processes can be adjusted. Given how strongly retention correlates with profitability, ending the relationship should be the last option rather than the first.
How accurate does the analysis need to be? Accurate enough to reveal meaningful differences between customers and support better decisions. A practical estimate available now beats a perfect allocation model that never gets finished.
How often should customer profitability be reviewed? At least annually for most established businesses, and quarterly for companies experiencing rapid growth, changing costs, constrained capacity, or highly variable customer requirements.
Who should participate in the review? Finance, sales, operations, customer service, and senior leadership, because each function sees costs and benefits the others do not.
The bottom line
The customers who generate the most revenue are not necessarily the customers who create the most profit, and the research suggests the gap between the two is far wider than most owners assume.
A serious customer profitability analysis looks past the invoice and asks what the business must invest to earn, deliver, collect, and keep that revenue, accounting for direct costs, support demands, exceptions, payment behavior, capacity, and risk. Sometimes it confirms what leadership already suspected. Sometimes it overturns assumptions that have shaped the sales strategy for a decade. Either result is worth having.
Once owners understand which relationships create sustainable value, they can price with more confidence, allocate capacity more intelligently, protect their people from the accounts that burn them out, and pursue the customers who fit the business they are actually trying to build.
The question is not only who buys the most from us. It is which customer relationships make the whole company stronger.
Source list for editorial verification
| Claim | Source | Link |
|---|---|---|
| Top 20% of customers generate 150–300% of total profits | Kaplan, R.S. and Narayanan, V.G. (2001), “Measuring and Managing Customer Profitability,” Journal of Cost Management, September/October, 5–15 | https://en.wikipedia.org/wiki/Customer_profitability (citation listing) |
| Kanthal case: 40% of customers produced 250% of profits; least profitable 10% consumed 120% | Kaplan (1989), as reported in Stockholm School of Economics research | http://arc.hhs.se/download.aspx?MediumId=181 |
| 59% of small businesses have invoices overdue 30+ days, up from 47%; $17.7K average owed; 49% cash flow gaps; 59% paid fees to access earned money | 2026 Small Business Late Payments Report, Intuit QuickBooks, July 2026 | https://quickbooks.intuit.com/r/small-business-data/small-business-late-payments-report-2026/ |
| Average 28.8 days to payment, invoices 9.0 days late, Q1 2026 | Xero U.S. Small Business Insights, as reported June 2026 | https://www.factorfinders.com/blog/invoice-payment-delays-in-2026/ |
| 5% retention increase raises profits 25–95% | Reichheld, Bain & Company, cited in Harvard Business Review, October 2014 | https://hbr.org/2014/10/the-value-of-keeping-the-right-customers |
| Single client at 10–15% of gross revenue signals concentration risk | Forbes Finance Council | Verify before publishing, see note below |
Editorial notes. The whale curve percentages vary between secondary sources, with some reporting the top band at 150 to 180 percent rather than 150 to 300. Cite the Kaplan and Narayanan paper directly rather than any blog repeating it. The Reichheld range is wide and industry-dependent, which the article states rather than hides. The Xero figure is attributed to Xero but reached through a secondary report, so link to Xero’s Small Business Insights directly if you can locate the original release. The Forbes concentration figure needs its exact URL confirmed before the article goes live.